Earthquake Insurance for California Homeowners
Earthquake coverage for California homes, which a standard homeowners policy does not include.

Your Homeowners Policy Doesn't Cover Earthquakes
A lot of people find this out too late. A standard homeowners policy in California leaves out earthquake damage. If the ground shakes and the house cracks, slides off its foundation, or has to come down, your homeowners policy won't pay to fix it. Earthquake insurance is a separate policy, added alongside the one you already have.
The biggest reason people call us about it is their equity. If a quake badly damages your home and you have no earthquake coverage, you still owe the mortgage. The house you've been paying down for years could need tens of thousands, or hundreds of thousands, of dollars in repairs before anyone can live in it again. Earthquake insurance is what stands between that damage and your savings.
Clients also tell us they worry that California is past due for a big one. Scientists don't predict the day, but they do estimate the odds. The U.S. Geological Survey puts the chance of at least one magnitude 6.7 or larger earthquake in the San Francisco Bay Area before 2043 at 72 percent (USGS). That's the number that makes most people stop and ask about coverage.
See My Earthquake Options
One Quake Damages Thousands of Homes at Once
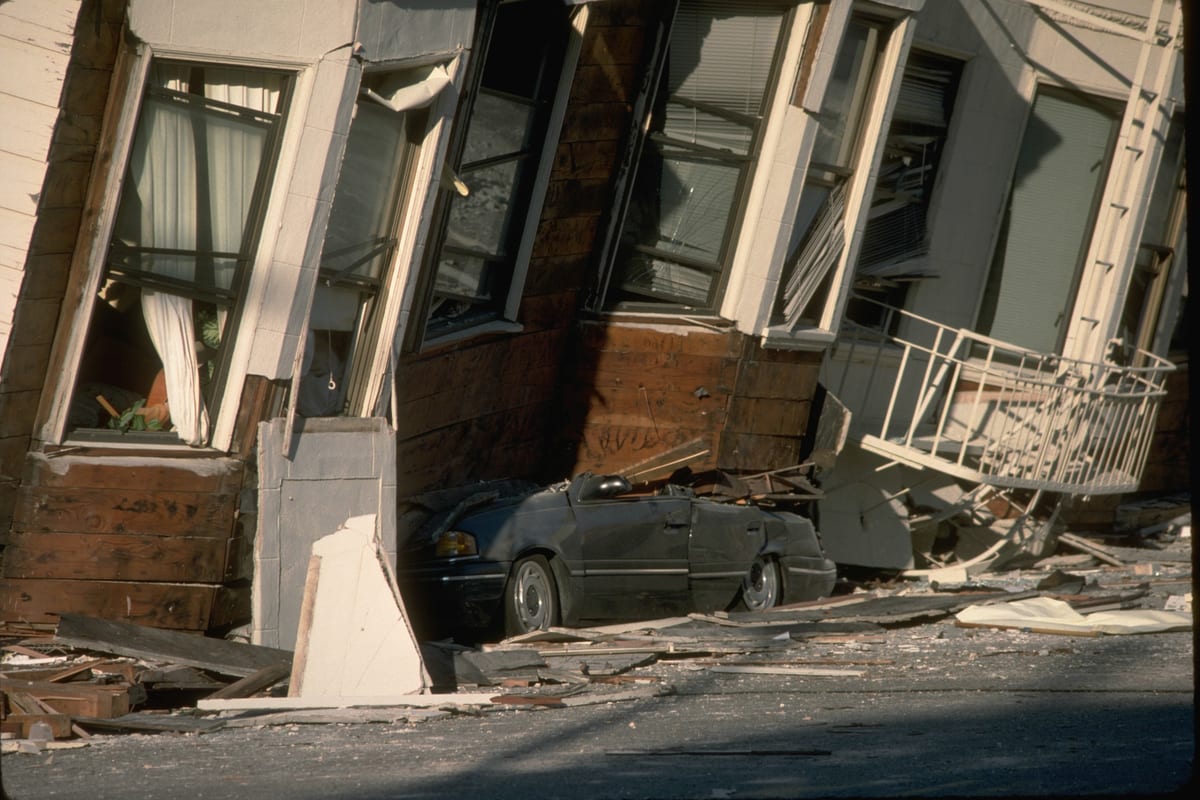
"On October 17, 1989, I was downtown in San Francisco, on the sidewalk outside Nordstrom with my nine-month-old son in my arms. They had just taken my car to park it. Then it hit. It was like time stood still, and the whole city changed right in front of me. We jumped in the car and drove through the city while all of it was happening, trying to get home over the Bay Bridge. We were one car away from getting on when they stopped us. Then we found out part of the bridge had collapsed. We turned around and spent the night with friends in San Mateo. I wasn't a homeowner yet, but I saw how fast it happened, and how many homes and lives were destroyed. Living where we do, that's why I take earthquake coverage so seriously."
A house fire usually hits one home. A large earthquake hits a whole region on the same morning. Thousands of homes can need repairs at the same time, and every one of those owners is calling the same contractors and looking for the same materials.
That's why earthquake coverage isn't something you can add after the fact. Companies often pause new earthquake policies in an area right after a quake. The time to have it is before, while it's available.
It's also why waiting for help after a disaster is a hard plan. Aid, when it comes, is often a loan you have to pay back, not a check to rebuild your home.
How the Earthquake Deductible Works
This is the question we get most, and it's a fair one. An earthquake deductible works differently from the deductible on your homeowners policy.
Most earthquake deductibles are a percentage of your dwelling coverage, not a flat dollar amount. Here's an example of the math. If your home is insured for $500,000 and you choose a 15 percent deductible, you'd cover the first $75,000 of damage to the house yourself, and the policy pays the rest up to your limit.
That sounds like a lot, and it is. So why do people still buy it? Because earthquake insurance is built for the loss you can't recover from, not the cracked tile. In a serious quake, damage to a home can run far past the deductible. Being on the hook for $75,000 is hard. Being on the hook for the whole house is harder.
This matters most if you own your home outright. All of that equity is yours, and without earthquake coverage, all of it is at risk. A deductible is an amount you can plan for, save toward, or, if you had to, borrow. Nobody wants to take out a loan, but it's an option. There's no loan that replaces a whole house you weren't insured for.
Many policies let you choose your deductible. A lower percentage means a higher premium, and a higher percentage lowers the cost. We walk through a few options with you, with real numbers for your home, so you can pick what fits your budget.
Older Home? A Retrofit Can Lower Your Cost
If your home was built before 1980 and sits on a raised foundation with a short crawl space wall, it may be a good candidate for a seismic retrofit. The work bolts the house to its foundation and braces that crawl space wall, so the house is less likely to slide off in a quake.
A retrofit can help in two ways. It can make the house safer, and it can lower what you pay for earthquake insurance. Policies through the California Earthquake Authority, for example, offer a discount of up to 25 percent on the premium for a qualifying retrofit. Other companies set their own rules, so we check what applies to the options we show you.
California also has a grant program, Earthquake Brace + Bolt, that helps pay for the retrofit in certain ZIP codes, with extra help for some lower-income households. It opens for applications on a schedule, and the amounts change, so check the official Earthquake Brace + Bolt site for what's available where you live.
Already retrofitted? Tell us when you call, and keep your paperwork from the contractor. It's the proof a company will ask for.
What Earthquake Insurance Covers
Policies differ, and the policy wording always decides. Most earthquake policies can include:
- The house itself, to repair or rebuild after quake damage.
- Your belongings, often as an option you can add or leave off.
- Somewhere to live while the home is being repaired, often called loss of use.
Some policies also offer help with things like emergency repairs or building code upgrades. We go through the coverages with you before you sign anything, not after, so you know what's in the policy and what isn't.
How Darlene Baxter Insurance Agency Handles Earthquake Insurance
Earthquake coverage is a big part of what Darlene Baxter Insurance Agency does. Michelle Henning, our personal insurance agent, handles our earthquake policies. She'll ask about your home, your current coverage, and how much of a deductible you could live with, then show you options side by side.
We start with our main company. When it isn't the right fit, we look at other companies available through our brokerage. If your home is on the FAIR Plan with a wrap policy, earthquake still isn't included, and we can help with that too.
We can't promise approval or a price. Those decisions belong to the insurance companies. You'll always know where things stand, and we offer a review at every renewal.
Earthquake Insurance Where We Work
The office is in Pleasant Hill, and the Bay Area is where earthquake questions come up most. The Calaveras fault runs through the San Ramon Valley, and the Concord fault runs through Concord. We help homeowners in Pleasant Hill, Walnut Creek, Concord, Lafayette, Martinez, San Ramon, Alamo and Danville.
We also insure homes in the foothills and mountains, in Tuolumne, Calaveras, El Dorado and Nevada counties. If you own a second home up there, ask us about earthquake coverage for it as well.
Talk to Us About Earthquake Coverage
Want to see what earthquake coverage would cost for your home, and what the deductible would look like? Call the office at (925) 940-6970, or send us a message. Tell us about your house.
Frequently Asked Questions
Does homeowners insurance cover earthquakes in California?
No. A standard California homeowners policy leaves out earthquake damage. You need a separate earthquake policy, which we can quote alongside your home.
How does an earthquake insurance deductible work?
Most earthquake deductibles are a percentage of your dwelling coverage. On a home insured for $500,000 with a 15 percent deductible, you'd pay the first $75,000 of damage to the house, and the policy pays the rest up to your limit.
Is earthquake insurance worth it with such a high deductible?
It's built for the loss you can't recover from. In a serious quake, repairs can cost far more than the deductible, and you still owe your mortgage. We show you real numbers for your home so you can decide.
Is there an earthquake insurance discount for a retrofitted home?
Often, yes. Policies through the California Earthquake Authority offer up to 25 percent off for a qualifying retrofit, and other companies set their own rules. Tell us about the retrofit and we'll check what applies.
Can I buy earthquake insurance right after an earthquake?
Usually not right away. Companies often pause new earthquake policies in an area after a quake. The time to get coverage is before.
Keep exploring
Want a second look at your coverage? Talk to Darlene Baxter Insurance Agency.